Burnham chaired £55.7m loan approvals after Manchester City hospitality
Andy Burnham chaired meetings approving loans to companies owned by Manchester City's owner after accepting hospitality from the club's chairman.
By James Reeve, Foreign Affairs Writer
Published 15 Oct 2026, 07:01
What happened
Andy Burnham chaired public authority meetings that approved £55.7 million in loans to property companies owned by Manchester City owner Sheikh Mansour bin Zayed bin Sultan Al Nahyan, after accepting football hospitality from the club's chairman.
The decisions were taken by the Greater Manchester Combined Authority (GMCA) in September and October 2017, when Burnham was mayor. They involved three businesses connected through their ownership to the Emirati politician, linking public development finance with the wider commercial interests behind the football club.
On 21 August 2017, Burnham attended Manchester City's home match against Everton at the Etihad Stadium as a guest of Khaldoon Al Mubarak, City's chairman and a close business associate of Sheikh Mansour. The hospitality was valued at £330.
Burnham, an Everton supporter, had dinner with Al Mubarak in an executive box before watching the Premier League game, which finished 1-1. The visit took place 39 days before the combined authority considered the first two property loans.
At that meeting, on 29 September at Trafford Town Hall, Burnham chaired proceedings as members considered financing for New Little Mill and Vesta Street. Both companies were owned by Sheikh Mansour through Jersey. The proposed borrowing was intended to support flats in Ancoats, north of Manchester city centre.
Burnham did not declare the August hospitality during that meeting. This places two separate aspects of public accountability alongside each other: the acceptance of a benefit from a business contact and the handling of a later decision involving companies connected to that contact.
The background
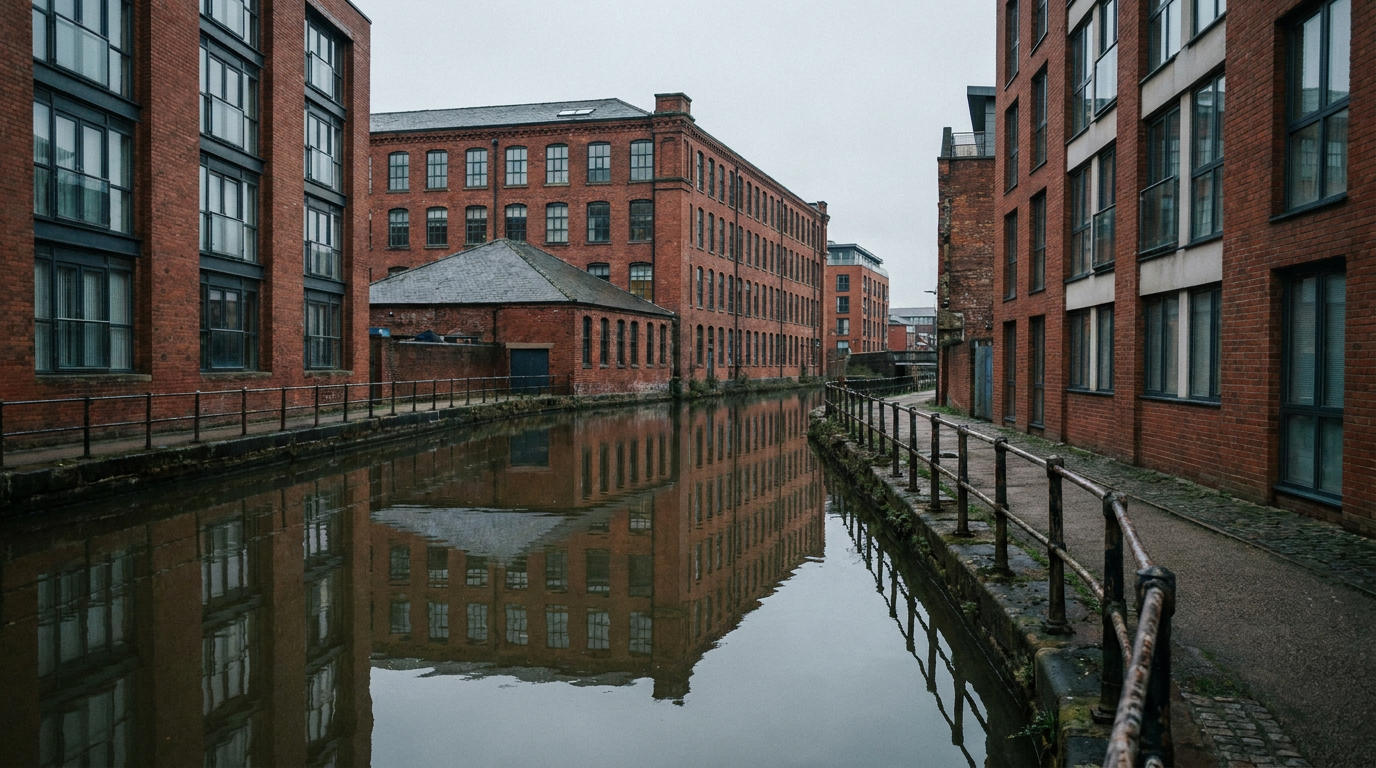
Ancoats contains former cotton mills and warehouses alongside canals, making the development proposals part of the conversion of Manchester's industrial neighbourhoods to residential use. The companies were seeking public finance for upmarket flats in an area undergoing regeneration.
The ownership connection extended beyond a shared association with Manchester. Sheikh Mansour owned Manchester City as well as the two September loan applicants, while Al Mubarak combined his position at the football club with a close business relationship with its owner. These were distinct organisations linked through individuals at the top.
The combined authority was the public decision-making body, rather than the football club or a private lender. Its voting membership at the time consisted almost entirely of Labour councillors. Burnham's role as chair placed him at the centre of the meetings, although the approvals were collective authority decisions rather than loans awarded by him personally.
A public loan is different from a grant. Lending provides money on terms that require repayment; a grant does not ordinarily carry the same repayment obligation. The amount approved for lending therefore represents public financing committed to a project, not automatically an equivalent permanent cost to taxpayers.
That distinction also matters when assessing risk. Public lending can return money to the lender, but repayment depends on the borrower meeting its obligations. The financial case for a development loan concerns both the purpose of the investment and the arrangements protecting the public money advanced.
Hospitality and lending belong to separate accountability processes. A hospitality record concerns a benefit received by an office-holder. A declaration at a meeting concerns the interests relevant to a particular item of business. Recording a gift and addressing its relevance to a later decision serve different purposes.
What people are saying
The combined authority's formal decisions set out its position on the September applications: it approved £10.5 million for New Little Mill and £20.7 million for Vesta Street. Together, those two commitments amounted to £31.2 million for businesses under the same ultimate ownership.
At a further meeting in October 2017, held at the Lowry Theatre and again chaired by Burnham, the authority approved another £24.5 million loan. The recipient was Lampwick Developments Limited, which also identified Sheikh Mansour as its ultimate beneficial owner.
An ultimate beneficial owner is the person who ultimately owns or controls a business, even where other companies sit between that person and the operating company. This makes the ownership of a loan applicant relevant beyond the name appearing on the application itself.
The October decision brought the combined value of the three approvals to £55.7 million. Lampwick's involvement extended the lending relationship beyond the two companies considered in September, while retaining the same connection to the Manchester City owner.
The decisions demonstrate the authority's agreement to provide financing. They should be distinguished from the separate question of how an individual participant handled hospitality: approval of a project and management of a potential conflict are different parts of the public decision-making process.
What happens next
The relationship continued into spring 2018. Burnham and Al Mubarak again had dinner in an executive box at the Etihad Stadium, this time before the Manchester derby. That hospitality was valued at £700, more than twice the value of the previous August's visit.
A month later, Burnham received two tickets to an Ed Sheeran concert at the stadium, worth £150. Across the Everton match, the derby visit and the concert tickets, the stated value of the benefits came to £1,180.
That chronology separates hospitality received before the 2017 lending decisions from benefits received afterwards. The August invitation preceded both approval meetings; the derby and concert visits followed them. Keeping that order clear is essential to understanding which benefits existed when each public decision was made.
For a public development loan, approval is one stage of a longer financial process. Loan administration involves the terms governing the borrowing, the release of funds and repayment. An approval total describes the scale of the lending decision; it does not, by itself, describe the eventual financial result.
The same distinction applies to the property projects. Financing a development and completing homes are separate steps, with different practical consequences. The decisions here concerned lending to companies, rather than the combined authority directly constructing or owning the proposed flats.
Why this matters
For Greater Manchester residents, the practical issue is the use of public finance to support privately owned housing developments. Such lending brings a public authority into a financial relationship with commercial borrowers. Understanding who ultimately owns those borrowers helps residents follow where public commitments sit within larger business networks, including those associated with major sporting institutions.
For readers elsewhere in the UK, the sequence illustrates why hospitality and meeting declarations address different questions. One records what an office-holder received; the other helps people understand the interests surrounding a decision. Alongside clear distinctions between loans, grants and completed spending, those records allow the public to assess both the financial commitment and the way it was authorised.
Reporting that informed this story
This article was written independently by The Daily Times from publicly available facts and headlines. No text has been copied from the outlets above.